Insights Page/Mutual Funds

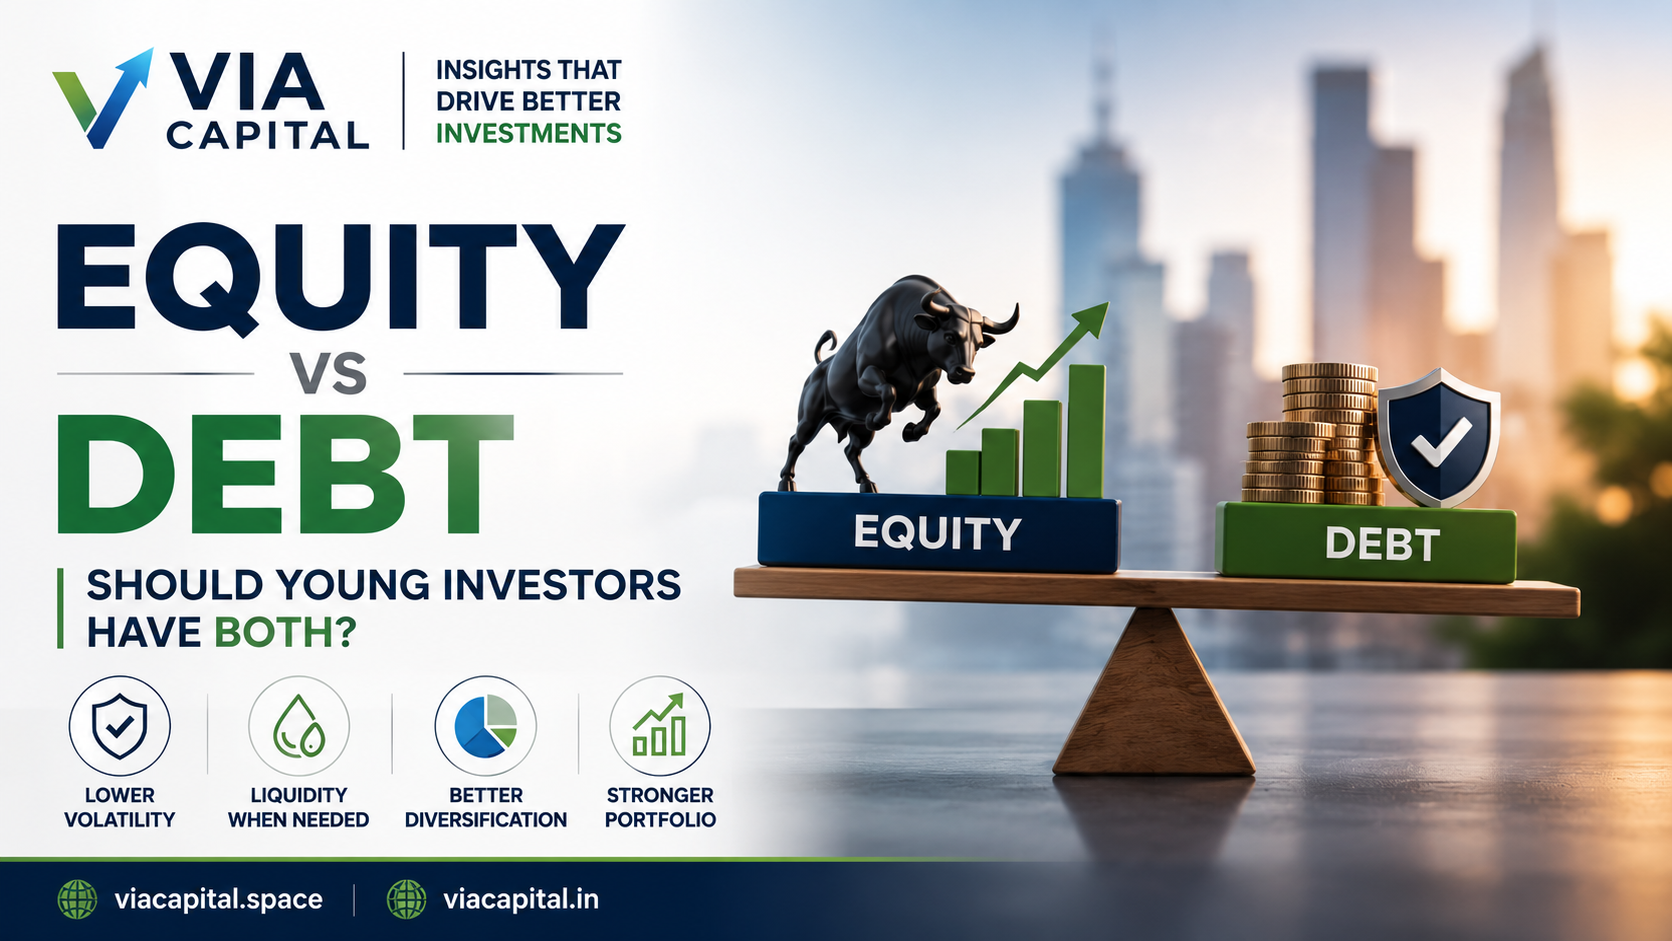
Why Young Investors Should Consider Debt Mutual Funds in Portfolio Planning

Young investors often prefer equity for long-term growth. Here's why adding debt mutual funds can help manage volatility, liquidity needs and portfolio risk.

Abhishek sharma
Editorial Lead
Updated August 30, 2026
5 Min Read
Why Young Investors Should Consider Debt Mutual Funds in Portfolio Planning

In 30 seconds

  • Young age does not mean 100% equity.
  • Debt can diversify portfolio risk.
  • Debt funds are not risk-free.
  • Match investments with your financial goals.
  • Review and rebalance your asset allocation.

Young investors in their 20s and 30s often prefer equity because they have a longer investment horizon and more time to handle market volatility.

But having a long time horizon does not automatically mean that a portfolio should be 100% equity. A debt allocation can provide diversification, liquidity and a source of relatively lower-volatility assets during difficult market periods.

What is happening

Recent discussions among financial professionals have highlighted the importance of asset allocation even for younger investors.

The argument is simple: equity can provide long-term growth, but markets can also fall sharply in the short term. Holding some debt alongside equity can help reduce concentration in a single asset class and may make it easier for investors to stay invested during market corrections.

This does not mean every young investor needs the same equity-to-debt ratio. The right allocation depends on income, financial goals, emergency savings, risk tolerance and when the money will be needed.

Key facts and data

Detail Figure Source
Mutual Fund Industry AUM – July 2026 ₹85.76 lakh crore AMFI
Average AUM – July 2026 ₹86.34 lakh crore AMFI
SIP Contribution – July 2026 ₹31,961 crore AMFI
Total Mutual Fund Folios – July 2026 28.09 crore AMFI
Retail-oriented Equity, Hybrid & Solution-Oriented Folios About 21.40 crore AMFI
Debt Fund Category Predominantly invests in debt and debt-related instruments SEBI
Equity Fund Category Predominantly invests in equity and equity-related instruments SEBI
Hybrid Fund Category Invests across permitted asset classes including equity and debt SEBI

AMFI reported that the Indian mutual fund industry's AUM stood at ₹85.76 lakh crore as of 31 July 2026, while monthly SIP contributions during July reached ₹31,961 crore. :contentReference[oaicite:1]{index=1}

The background you need

SEBI broadly classifies mutual fund schemes into categories including equity schemes, debt schemes, hybrid schemes, life cycle funds and other schemes.

A debt mutual fund predominantly invests in debt and debt-related instruments, while an equity mutual fund predominantly invests in equity and equity-related instruments. Hybrid funds combine different permitted asset classes. :contentReference[oaicite:2]{index=2}

Equity Funds

Equity funds primarily invest in shares and equity-related securities.

They can offer higher long-term growth potential, but their value can fluctuate significantly when stock markets move sharply.

Debt Mutual Funds

Debt funds invest primarily in instruments such as government securities, corporate bonds and money-market instruments.

They generally have lower equity-market exposure, but they are not risk-free. Their returns can be affected by interest-rate movements, credit quality and liquidity conditions.

Hybrid Funds

Hybrid funds combine different asset classes within one scheme.

For investors who do not want to manage separate equity and debt allocations themselves, certain hybrid categories can provide a structured way to diversify across asset classes.

Why can debt matter for young investors?

Being young gives an investor more time to recover from market downturns, but it does not remove short-term financial needs.

A person in their 20s or 30s may need money for an emergency, education, a home purchase, a career transition or another major expense. If all investments are in equity when the money is needed, a market correction can make the timing particularly uncomfortable.

Reducing portfolio concentration

A portfolio invested entirely in one asset class is exposed to the risks of that asset class.

Adding debt can diversify the portfolio and potentially reduce overall volatility. The objective is not necessarily to maximise returns every year, but to build a portfolio that an investor can continue holding through different market conditions.

Managing short-term goals

Money required in the near term generally should not be exposed to the same level of market risk as long-term wealth-building money.

Depending on the goal and risk profile, investors may consider lower-risk instruments or suitable debt-oriented mutual fund categories for money that does not need equity-like growth.

However, debt funds still carry investment risks and should not be treated as a guaranteed-return product.

Helping investors stay disciplined

A sharp equity-market correction can test even experienced investors.

Having a diversified portfolio can reduce the pressure to sell equity investments simply because markets have fallen. The real benefit of asset allocation is often not just mathematical—it can also help investors maintain discipline.

What financial professionals are highlighting

The broader message from wealth-management professionals is that asset allocation should not be based only on age.

Young investors can have a higher equity allocation because of their longer investment horizon, but the portfolio should still account for liquidity requirements, financial goals and the investor's ability to tolerate losses.

The objective is to find a balance between growth, liquidity and risk management rather than treating equity and debt as an either-or decision.

Debt Mutual Funds vs Fixed Deposits

Debt mutual funds and bank fixed deposits are different products and should not be treated as interchangeable.

A fixed deposit generally provides a predetermined interest rate for a specified tenure, subject to the bank's terms.

Debt mutual fund returns are linked to the performance of the securities held by the scheme and can fluctuate. There is no guaranteed return simply because a fund invests in debt securities.

Investors should therefore compare the risk, liquidity, taxation, duration and underlying portfolio before choosing between the two.

What about emergency funds?

Emergency money should primarily focus on accessibility and capital stability rather than chasing returns.

Many investors use savings accounts, sweep facilities, fixed deposits or other suitable low-risk instruments for emergency reserves. Some debt-oriented mutual fund categories can provide liquidity, but they still carry market and credit risks.

Therefore, a debt mutual fund should not automatically be described as an emergency fund.

What this means for investors

The key lesson for young investors is that long-term investing does not mean ignoring risk management.

Equity can remain an important growth engine for a young investor, but debt and other relatively lower-risk assets can provide diversification and liquidity.

Instead of asking whether a young investor should invest only in equity or only in debt, the better question is how much risk the investor can realistically take while still meeting upcoming financial goals.

A practical portfolio review should consider:

  • Investment horizon: When will the money actually be needed?
  • Risk tolerance: How much temporary loss can the investor tolerate?
  • Emergency savings: Are essential expenses already covered separately?
  • Income stability: Is the investor's income predictable?
  • Financial goals: Are the investments linked to short-, medium- or long-term objectives?
  • Rebalancing: Does the portfolio still match the intended asset allocation after market movements?

What to watch next

  • AMFI monthly data: Track mutual fund AUM, SIP contributions and investor folios.
  • Interest rates: Changes in interest rates can influence debt-fund performance, particularly for funds holding longer-duration securities.
  • Credit quality: Investors should monitor the credit quality of securities held by debt schemes.
  • Asset allocation: Review whether the portfolio still matches the investor's goals and risk tolerance.
  • Tax rules: Check the applicable tax treatment before investing because taxation can vary by fund structure, holding period and investor circumstances.

Frequently asked questions

Should young investors avoid debt mutual funds?

No. Age alone does not determine the appropriate asset allocation. Young investors may have a greater capacity for equity risk, but debt and other lower-risk assets can still play a role in diversification and liquidity.

Are debt mutual funds risk-free?

No. Debt mutual funds can be affected by interest-rate movements, credit events and liquidity conditions. They do not offer the same guaranteed-return structure as a fixed deposit.

Do debt funds give fixed returns?

No. The return from a debt mutual fund is not guaranteed. It depends on the performance of the securities held by the scheme and market conditions.

Can debt mutual funds be used for emergency money?

Some investors may use highly liquid, lower-risk debt-oriented products for short-term liquidity, but debt funds are not risk-free. Emergency reserves should be selected based on accessibility, capital stability and the investor's circumstances.

Should a 25-year-old invest only in equity?

Not necessarily. A young investor may have a longer horizon and therefore greater capacity for equity exposure, but the appropriate allocation depends on financial goals, income stability, risk tolerance and liquidity requirements.

What is the difference between equity and debt mutual funds?

Equity funds predominantly invest in equity and equity-related instruments, while debt funds predominantly invest in debt and debt-related instruments. Equity generally carries higher market volatility, while debt funds have different risks including interest-rate, credit and liquidity risk. :contentReference[oaicite:3]{index=3}

This article is published by VIA Capital for educational and informational purposes only. It does not constitute financial advice, investment advice, or a recommendation to buy or sell any security. Investors should consider their own financial circumstances and consult a SEBI-registered investment adviser where appropriate.

Why it matters

Young investors have time on their side, but they can still face market corrections and unexpected financial needs. Understanding how equity, debt and hybrid investments work can help build a portfolio that balances long-term growth with diversification and liquidity.

Sources

Educational content only. This article is published purely for educational and informational purposes and does not constitute personalized investment advice, buy/sell calls, or financial recommendations.

Written by

Abhishek sharma

Discussion (0)

Log in to join the conversation.

Sign In to Comment