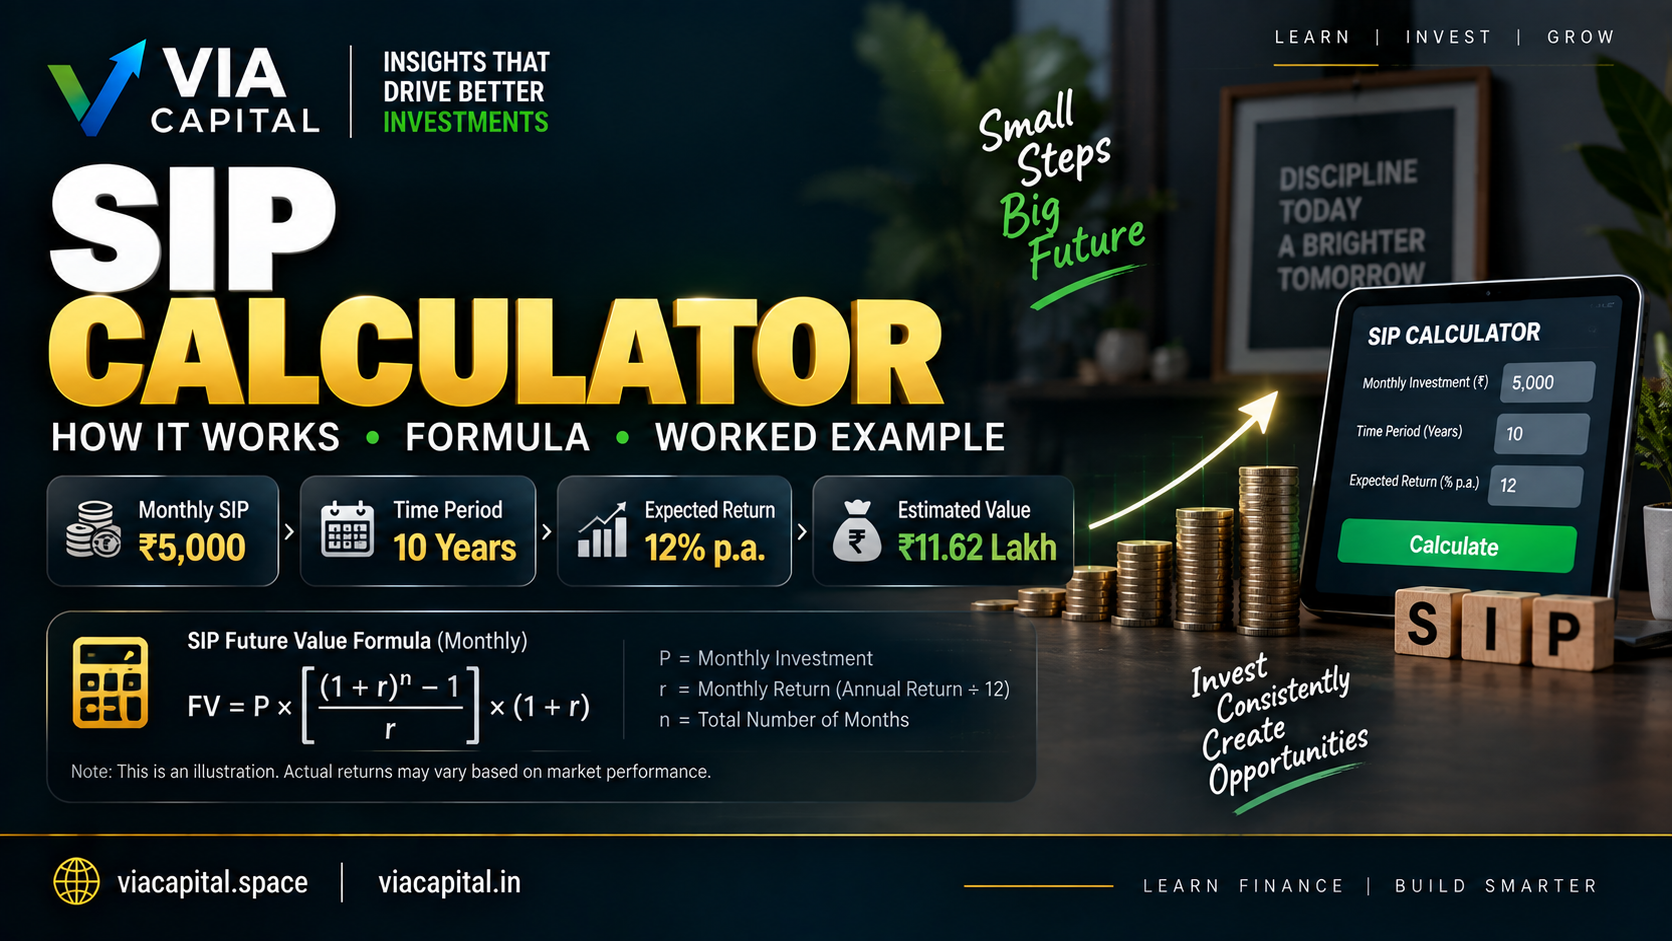
There is a moment in every financial decision where you stop reading and start calculating. Project the future value of a monthly Systematic Investment Plan. This guide is written for that moment. Plain language, one worked example, and a calculator you can open in the next line if you would rather skip straight to your own figures.
Image placeholder — add a screenshot or illustration for this article here.
👉 Straight to the tool: Open the SIP Calculator
What is going on behind the number
A SIP invests a fixed amount every month into a mutual fund. Because you buy more units when prices are low and fewer when high (rupee-cost averaging), your average cost smooths out over time.
The formula behind it:
FV = P × [((1 + r)^n − 1) / r] × (1 + r)
| Symbol | What it means |
|---|---|
FV |
Future value at maturity |
P |
Monthly investment amount |
r |
Monthly rate = annual rate ÷ 12 ÷ 100 |
n |
Total number of months (years × 12) |
Nothing is rounded away quietly and nothing is assumed on your behalf. If a figure appears in the result, it came from something you entered.
An example, start to finish
₹5,000/month for 20 years at 12% annual return → invested ₹12,00,000, projected value ~₹50 lakh.
Change any one input and watch the result move — that sensitivity is the real lesson. It is far more useful than memorising a single outcome, because your own rate, tenure or contribution will never match the example exactly.
Using the SIP Calculator, step by step
- Open the SIP Calculator.
- Enter your figures. Use the ones on your statement, sanction letter or scheme document rather than a remembered number.
- Read the result card — the headline figure plus the breakdown that produced it.
- Adjust one input at a time to see what genuinely moves the outcome.
- Tap Download PDF to keep a copy of the calculation, with your inputs and assumptions printed on it.
The PDF takes a few seconds to build because it is a properly typeset report, not a screenshot. You will see a progress message while it is being prepared, and the download starts on its own.
What experienced users do differently
- Start early to maximize compounding.
- Step-up your SIP as your income increases.
Mistakes we see again and again
- Stopping SIPs during market downturns.
If you want to go a level deeper afterwards, read up on rupee cost averaging and xirr vs cagr. Both come up the moment you start comparing options seriously.